Global markets open mixed amid ongoing tech selloff, Middle East risks
ENGLISH 26.10.2026 - 10:45, Güncelleme: 26.10.2026 - 10:45
 

Global markets open mixed amid ongoing tech selloff, Middle East risks
AI profitability fears, US-Iran tensions weigh on investors ahead of upcoming rate decisions by Fed, ECB, BoJ
Global markets ended the week of Oct. 23 on a negative note and opened mixed Monday, as concerns over artificial intelligence (AI) financing, signals from corporate earnings and risks in the Middle East continued into the new week. The potential for renewed US-Iran tensions after the November midterm elections continues to dampen risk appetite. All eyes have turned to the Fed’s monetary policy decision this week, when the bank is expected to maintain its rates, but its forward guidance will be crucial in assessing the bank’s policy roadmap amid inflationary pressures. US economic growth, personal consumption data and earnings from Amazon, Microsoft and Alphabet will be on the agenda this week. Meanwhile, US President Donald Trump is reportedly considering dropping “the mother of all bombs” on Iran. “It’s not nuclear at all, this is just an extremely large bomb — it’s like a tiny nuclear bomb,” the president said during an interview last week. December-delivery Brent crude oil fell 1.9% to $114.50 a barrel after Qatari mediators reportedly traveled to Tehran to mediate talks with the US. The 10-year US Treasury yield is down three basis points at 4.97% amid increased demand for safe-haven assets. The US dollar index fell 0.2% to 101.7 amid declining bond yields, while the falling dollar supported a 0.5% increase in the price of gold, bringing it to $4,015 per ounce. At the same time, Luiz Inacio Lula da Silva won the second round of Brazil’s presidential election, unofficial results showed. The US dollar/Brazilian real exchange rate fell 0.1% to 4.9780. The results, which defied expectations, drove down an exchange-traded fund (ETF) of Brazilian stocks traded in Tokyo by about 15%. The New York Stock Exchange closed lower on Oct. 23 amid selling pressure on tech stocks as concerns over the profitability of AI investments continued, spilling over into other sectors. Telecommunications stocks dropped amid reports that SpaceX is in talks with cellular companies in the US to build a nationwide wireless network. Concerns over increasing competition drove down shares of carrier AT&T by 7.96%, while Verizon shares dropped 1.18% and T-Mobile shares fell 7.71%. SpaceX shares rose 1.89% at the same time. American Express shares fell 3.62% after its decision to lay off around 5% of its global workforce despite an increase in revenue and profit in the third quarter. Meanwhile, the University of Michigan’s consumer sentiment index was revised upward to 48 in October, but it remained at its lowest level in five months. The US manufacturing Purchasing Managers’ Index (PMI) hit a 53-month high, reaching 56 and defying expectations. The Dow Jones Industrial Average fell 1.23%, the S&P 500 declined 0.52% and the Nasdaq Composite was down 0.21% on Oct. 23. US indexes started Monday on a positive note. At the same time, European markets closed lower on Oct. 23 amid ongoing protests in France and rising oil prices. France’s 10-year bond yield surged to 5.07%, its highest level since 2002. Credit rating agency Moody’s said France’s “Aa3” rating is supported by its wealthy and diversified economy and strong public institutions, while noting that its fragmented political structure, instability, high debt burden and weakening debt-service metrics remain challenges. The eurozone’s manufacturing PMI came in slightly below expectations at 52.4 in October, while Germany’s manufacturing PMI exceeded estimates at 52.8 during the same period. France’s composite PMI fell from 51.1 to 48.4 in October, according to preliminary data, marking its lowest level in four months. All eyes have turned to the European Central Bank’s (ECB) monetary policy decision this week, when the bank is expected to maintain its three key policy rates. The bank may have to choose between fighting inflation and supporting economic activity if energy costs keep rising and the growth outlook for the European economy remains weak, analysts say. Germany's DAX 40 fell 0.75%, the UK's FTSE 100 declined 0.32% and France's CAC 40 was down 0.36%, while Italy's FTSE MIB 30 rose 0.36% on Oct. 23. European indexes started Monday on a positive note. Near Monday’s close, Asian equity markets are trading lower except in Hong Kong, as losses on the New York Stock Exchange spilled over into the region. China’s persistent domestic demand concerns continue to put selling pressure on the country’s stock markets. The Bank of Japan’s (BoJ) rate decision will be closely watched this week, although the bank is not expected to change its policy rates. Near the close of trading, Japan’s Nikkei 225 fell 0.3%, China’s Shanghai Composite dropped 0.2% and South Korea’s Kospi was down 0.7%, while Hong Kong's Hang Seng climbed 0.4%.
AI profitability fears, US-Iran tensions weigh on investors ahead of upcoming rate decisions by Fed, ECB, BoJ

Global markets ended the week of Oct. 23 on a negative note and opened mixed Monday, as concerns over artificial intelligence (AI) financing, signals from corporate earnings and risks in the Middle East continued into the new week.

The potential for renewed US-Iran tensions after the November midterm elections continues to dampen risk appetite.

All eyes have turned to the Fed’s monetary policy decision this week, when the bank is expected to maintain its rates, but its forward guidance will be crucial in assessing the bank’s policy roadmap amid inflationary pressures.

US economic growth, personal consumption data and earnings from Amazon, Microsoft and Alphabet will be on the agenda this week.

Meanwhile, US President Donald Trump is reportedly considering dropping “the mother of all bombs” on Iran. “It’s not nuclear at all, this is just an extremely large bomb — it’s like a tiny nuclear bomb,” the president said during an interview last week.

December-delivery Brent crude oil fell 1.9% to $114.50 a barrel after Qatari mediators reportedly traveled to Tehran to mediate talks with the US.

The 10-year US Treasury yield is down three basis points at 4.97% amid increased demand for safe-haven assets.

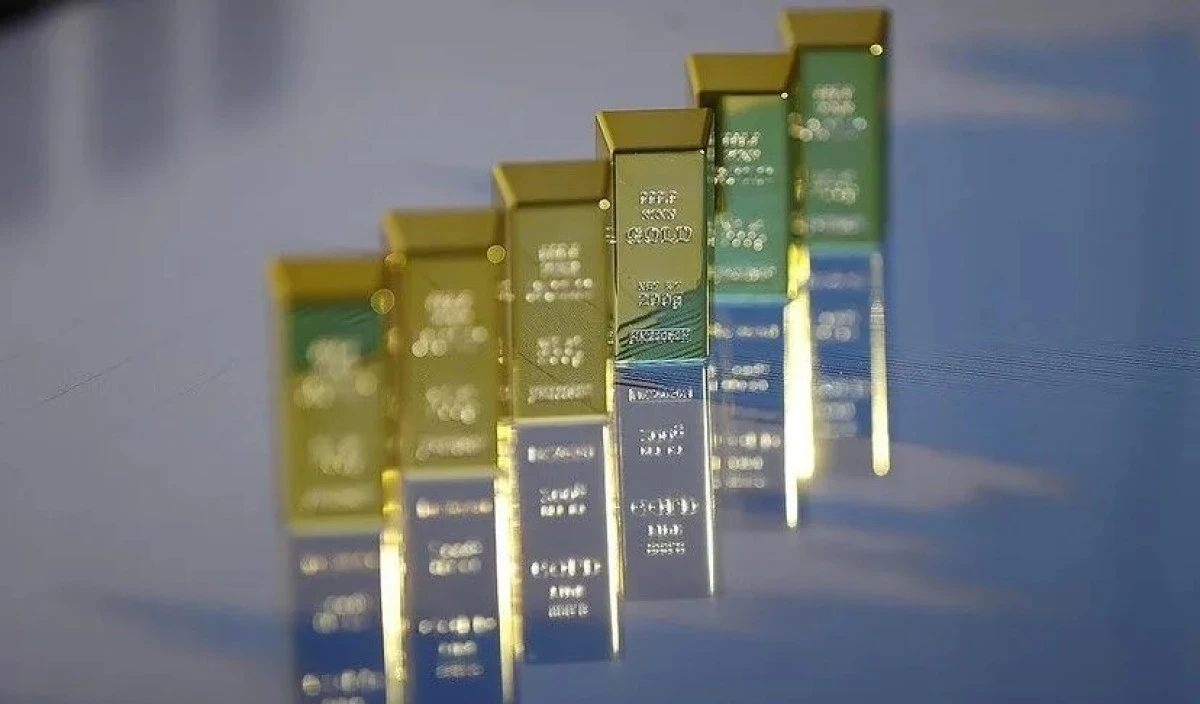
The US dollar index fell 0.2% to 101.7 amid declining bond yields, while the falling dollar supported a 0.5% increase in the price of gold, bringing it to $4,015 per ounce.

At the same time, Luiz Inacio Lula da Silva won the second round of Brazil’s presidential election, unofficial results showed. The US dollar/Brazilian real exchange rate fell 0.1% to 4.9780.

The results, which defied expectations, drove down an exchange-traded fund (ETF) of Brazilian stocks traded in Tokyo by about 15%.

The New York Stock Exchange closed lower on Oct. 23 amid selling pressure on tech stocks as concerns over the profitability of AI investments continued, spilling over into other sectors.

Telecommunications stocks dropped amid reports that SpaceX is in talks with cellular companies in the US to build a nationwide wireless network.

Concerns over increasing competition drove down shares of carrier AT&T by 7.96%, while Verizon shares dropped 1.18% and T-Mobile shares fell 7.71%. SpaceX shares rose 1.89% at the same time.

American Express shares fell 3.62% after its decision to lay off around 5% of its global workforce despite an increase in revenue and profit in the third quarter.

Meanwhile, the University of Michigan’s consumer sentiment index was revised upward to 48 in October, but it remained at its lowest level in five months.

The US manufacturing Purchasing Managers’ Index (PMI) hit a 53-month high, reaching 56 and defying expectations.

The Dow Jones Industrial Average fell 1.23%, the S&P 500 declined 0.52% and the Nasdaq Composite was down 0.21% on Oct. 23. US indexes started Monday on a positive note.

At the same time, European markets closed lower on Oct. 23 amid ongoing protests in France and rising oil prices.

France’s 10-year bond yield surged to 5.07%, its highest level since 2002.

Credit rating agency Moody’s said France’s “Aa3” rating is supported by its wealthy and diversified economy and strong public institutions, while noting that its fragmented political structure, instability, high debt burden and weakening debt-service metrics remain challenges.

The eurozone’s manufacturing PMI came in slightly below expectations at 52.4 in October, while Germany’s manufacturing PMI exceeded estimates at 52.8 during the same period.

France’s composite PMI fell from 51.1 to 48.4 in October, according to preliminary data, marking its lowest level in four months.

All eyes have turned to the European Central Bank’s (ECB) monetary policy decision this week, when the bank is expected to maintain its three key policy rates.

The bank may have to choose between fighting inflation and supporting economic activity if energy costs keep rising and the growth outlook for the European economy remains weak, analysts say.

Germany's DAX 40 fell 0.75%, the UK's FTSE 100 declined 0.32% and France's CAC 40 was down 0.36%, while Italy's FTSE MIB 30 rose 0.36% on Oct. 23. European indexes started Monday on a positive note.

Near Monday’s close, Asian equity markets are trading lower except in Hong Kong, as losses on the New York Stock Exchange spilled over into the region.

China’s persistent domestic demand concerns continue to put selling pressure on the country’s stock markets.

The Bank of Japan’s (BoJ) rate decision will be closely watched this week, although the bank is not expected to change its policy rates.

Near the close of trading, Japan’s Nikkei 225 fell 0.3%, China’s Shanghai Composite dropped 0.2% and South Korea’s Kospi was down 0.7%, while Hong Kong's Hang Seng climbed 0.4%.

Habere ifade bırak !
Habere ait etiket tanımlanmamış.
Okuyucu Yorumları (0)

Yorumunuz başarıyla alındı, inceleme ardından en kısa sürede yayına alınacaktır.
Yorum yazarak Topluluk Kuralları’nı kabul etmiş bulunuyor ve turkishpress.co.uk sitesine yaptığınız yorumunuzla ilgili doğrudan veya dolaylı tüm sorumluluğu tek başınıza üstleniyorsunuz. Yazılan tüm yorumlardan site yönetimi hiçbir şekilde sorumlu tutulamaz.
Sitemizden en iyi şekilde faydalanabilmeniz için çerezler kullanılmaktadır, sitemizi kullanarak çerezleri kabul etmiş saylırsınız.